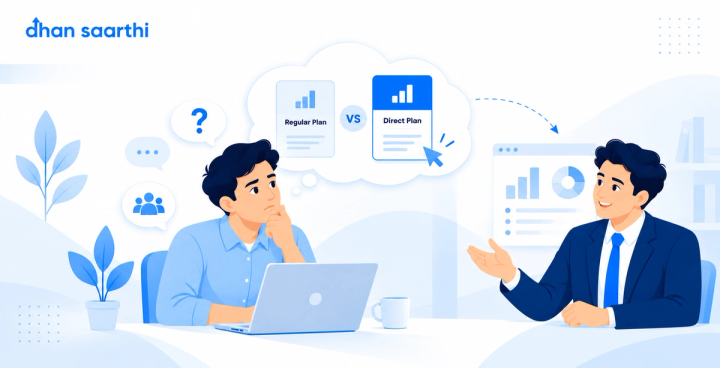
Mutual Fund Distributors (MFDs) often lose the regular-vs-direct-plan conversation not because the client is wrong about the expense ratio, but because the advisor argues the cost point instead of shifting to what the fee actually buys. This article gives you a calmer, five-step framework — validating the question, separating the fund from the decision, and pointing to specific value you've already delivered — so the conversation builds trust instead of sounding defensive.
Why This Question Feels Loaded — And Why It Shouldn't
Regular and direct plans of the same mutual fund scheme carry different expense ratios, and that difference in cost compounds over the years. Clients who read even a little about investing eventually come across this fact — usually through one of these channels:
- 1. A finance blog explaining expense ratios.
- 2. A YouTube video comparing plan costs.
- 3. A forwarded WhatsApp message that frames it as "you're being overcharged."
The problem isn't that the client asked the question. The problem is that most advisors have never rehearsed an answer, so the question catches them off guard and they respond emotionally instead of clearly.
The Core Mistake: Answering a Cost Question With a Cost Answer
When a client asks about the cost difference, most advisors try to argue the cost point directly. This usually shows up as one of these reactions:
- 1. Minimising the expense ratio difference.
- 2. Disputing the figure the client has seen.
- 3. Getting visibly uncomfortable with the topic.
All three are losing moves, because the client is factually right about the expense ratio difference. Arguing a true fact makes you look evasive.
The better move is to accept the fact calmly and shift the conversation to what the fee difference actually buys — because for most clients, it isn't a fund selection problem, it's a behaviour and decision-making problem. That is where an advisor's actual value shows up, and it's a claim you can defend with your own track record rather than an industry statistic.
A Conversation Framework That Doesn't Sound Defensive
Step 1
Validate the question
Open by agreeing with the premise instead of resisting it. Something like: "You're right to ask this — the direct plan does have a lower expense ratio, and you should know that." Agreeing first removes the adversarial tone from the conversation immediately.
Step 2
Separate "the fund" from "the decision"
Explain that the underlying scheme performance is identical between regular and direct plans, and the difference is purely in what is deducted for distribution. Then pivot: "The real question isn't which plan is cheaper — it's who is managing the decisions around this money over the next 10–15 years."
Step 3
Point to specific decisions you've already made for them
This is the part most advisors skip. Instead of speaking in generalities about "guidance" and "support," reference something concrete from their own portfolio history — for example:
- A fund switch you flagged at the right time.
- A SIP top-up you suggested after a salary hike.
- A panic call you talked them out of during a market fall.
Specific memory beats abstract value language every time.
Step 4
Be honest about who doesn't need an advisor
Counterintuitively, this builds trust rather than losing it. Tell the client plainly that the direct plan probably makes sense for them if they are someone who:
- Reviews their own portfolio regularly.
- Doesn't panic during corrections.
- Enjoys researching funds independently.
Most clients, when told this, self-select back toward the regular plan — because they recognise they're not that person, and they respect you more for not pretending otherwise.
Step 5
Close without pressure
End the conversation by handing the decision back to the client rather than pushing an outcome: "It's your money and your call — I just want you deciding this with the full picture, not just the expense ratio." Clients rarely leave a conversation that ends this way, because there was nothing to push back against.
What Not to Say
A few responses tend to backfire regardless of how well-intentioned they are:
- 1. Downplaying or disputing the expense ratio difference — clients can verify this themselves in minutes.
- 2. Implying that direct plan investors "get it wrong" or make poor decisions as a category — this reads as anti-client and undermines trust.
- 3. Making vague claims about "returns being better" through an advisor without pointing to anything specific — this sounds like a sales line, not a fact.
- 4. Turning the conversation into a guilt trip about loyalty or relationship history — this pressures the client instead of informing them.
Make This a Standing Conversation, Not a One-Time Rescue
The advisors who handle this question best aren't reacting for the first time when it comes up — they've already built a habit of showing their work throughout the year:
- 1. Flagging a rebalancing need before the client asks.
- 2. Sending a portfolio update after a volatile quarter.
- 3. Calling out a goal that's falling behind schedule.
When the direct-plan question eventually arrives, it lands on a relationship that has already demonstrated its value, not one that has to argue for it on the spot.
How Dhan Saarthi Helps You Show Your Work
Dhan Saarthi gives MFDs a structured way to document and surface the advisory decisions that are easy to forget in the moment but matter most in a direct-plan conversation — all in one advisor dashboard:
- 1. Portfolio review history.
- 2. Fund switch rationale.
- 3. SIP step-up recommendations.
- 4. Client communication logs.
Instead of relying on memory to recall what you did for a client two years ago, you can pull up a documented history in seconds — turning an abstract "I add value" claim into a concrete, client-specific record.
Conclusion
The regular vs direct plan question isn't going away, and it shouldn't be treated as an attack. Clients who ask it are usually engaged, not disloyal. The advisors who handle it well are the ones who stop defending the fee structure and start demonstrating, with specifics, what the fee actually pays for. That shift — from justification to evidence — is what keeps clients from feeling like they need to choose between saving money and being well-advised.